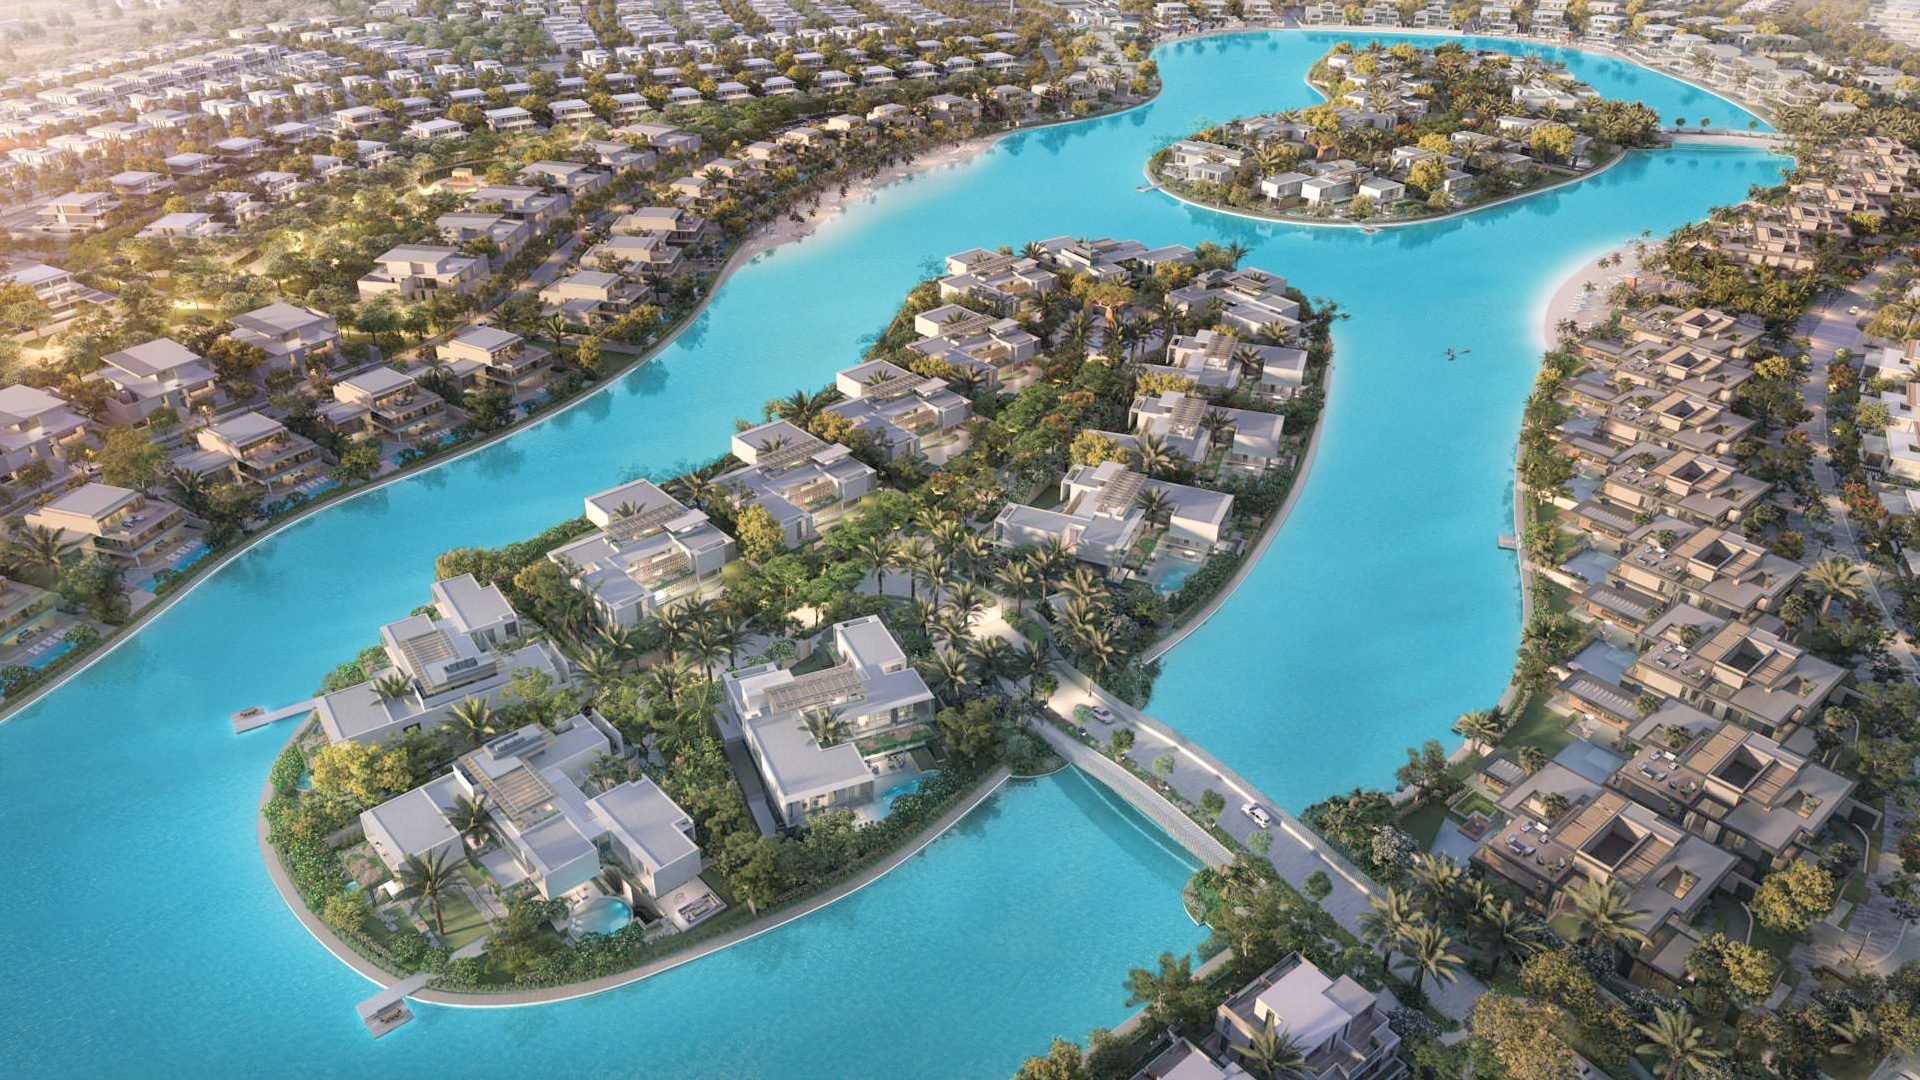
May recorded 17 transactions across Tilal Al Ghaf, down 19% from April's 21. A quieter month by volume, though activity stayed spread across the community's core villa segments rather than concentrating in any single area. Aura Gardens led with five sales, followed by Elan with four, Harmony 2 with three, Alaya Gardens and Harmony 1 with two each, and Amara with one. Pricing eased across most configurations and should be read against small sample sizes, with several tiers resting on a single transaction. The standout was an Alaya Gardens Retreat at AED 17M. The ultra-premium tier recorded no transfers, consistent with recent months.
Transaction Volume
| Sub-Community | Sales | MoM Change |
|---|---|---|
| Aura Gardens | 5 | −29% |
| Elan | 4 | +33% |
| Harmony 2 | 3 | 0 → 3 |
| Alaya Gardens | 2 | +100% |
| Harmony 1 | 2 | No change |
| Amara | 1 | −67% |
Aura & Aura Gardens
Aura Gardens was the joint most active sub-community with five sales, though the 3BR average requires care before it is read as a trend. A single transaction at AED 1.395M sits well below anything else recorded in this configuration and is what produces both the 26.41% monthly fall and the 17.84% annual one. The upper end of the range at AED 4.14M is the relevant benchmark for standard stock, and that figure sits comfortably within the band the 3BR has traded in all year. I would not treat either percentage as a market movement. Twin Villas offered a much cleaner read, trading between AED 6.70M and AED 7.00M and 20.70% ahead year-on-year, which is one of the strongest annual figures in the completed segment. Aura recorded no transfers after three in April, and the Aura Gardens 4BR was similarly quiet after four. Aura Gardens remains one of the most liquid areas in the community, supported by its price point, family-friendly layouts and relative accessibility.
Elan
Elan recorded four transactions split evenly between 3BR and 4BR, and remains flat year-on-year on both. Both configurations eased on the month, but the annual position is unchanged: Elan has now been level year-on-year in every month of 2026. For a fully handed-over community five months into the year, that consistency is the most useful thing about it. As one of the earliest handed-over clusters, Elan continues to benefit from ready availability, a mature community feel and a more accessible price point than the larger villa communities. It remains the clearest entry point into Tilal Al Ghaf for buyers who want to move in rather than wait.
Harmony
Harmony 2's two 4BR sales averaged AED 9.825M and were 15.93% ahead year-on-year, the strongest Harmony figure of the month. Five transactions across Phases 1 and 2, holding Harmony's position as Tilal Al Ghaf's primary completed end-user villa community. The Harmony 2 4BR is the cleanest data point, with two sales in a tight AED 9.65M to AED 10.00M band and one reaching AED 10M, reinforcing the premium buyers will pay for completed family homes in well-positioned parts of the community. Harmony 1's monthly declines follow April's exceptional prints of AED 10.85M and AED 11.80M, which were the highest of the year. Measured against those, a fall was always likely; the 4BR remains 12.00% ahead year-on-year, which is the more reliable number. The Harmony 2 5BR sale at AED 7.50M sits materially below the wider market range and 23.47% below the same point last year. On a single transaction I would treat it as an outlier unless further comparables emerge.
Alaya & Alaya Gardens
The standout sale of the month was an Alaya Gardens Retreat at AED 17M, one of the strongest individual transactions in May. Both Alaya Gardens tiers are within a few percent of where they sat twelve months ago, at −2.30% and −4.00%. With the community still under construction, that stability is a reasonable position rather than a concerning one. The Retreat occupies an important place in the market: a larger, more elevated home than Harmony or Amara, while sitting below Alaya Beach, Elysian Mansion and Serenity Mansion. As the community progresses I expect Alaya Gardens to become increasingly relevant for buyers seeking size, quality and long-term value without stepping into the mansion bracket. Alaya itself recorded no transfers for a third consecutive month. Limited availability and firm seller expectations are the constraint, not demand.
Amara
Amara recorded one Twin Villa at AED 7.90M, softer than April's average but a single data point rather than a wider repricing. The community has now traded across a AED 7.90M to AED 10.50M range this year, and where any individual sale falls within that band depends heavily on plot and specification. At −4.47% year-on-year Amara is broadly level over twelve months. Amara remains well positioned, offering modern layouts, strong internal space and a more accessible price point than completed Harmony stock or the larger premium communities. I expect buyer focus to sharpen as the build progresses, particularly among end-users looking for newer product at a still-attractive price per sq ft.
Elysian Mansion, Serenity Mansion & Lanai Islands
The ultra-premium tier recorded no transactions in May, continuing the recent pattern of limited activity at the top of the community. This should not be read as a lack of demand. The constraints remain access, construction progress and seller expectations. Buyer interest persists, but transactions are likely to stay selective until there is greater clarity on completion, views, landscaping and final delivery. Once buyers can properly assess the finished product, I expect activity in the mansion segment to become more visible. January's AED 52M Elysian Muse remains the reference point for where this tier can trade.
Notable Sales
Key Takeaways
Volume softened to 17 deals, down 19% on April
A quieter month, though activity stayed spread across six sub-communities rather than concentrated in one area. May is the first month this year below 21 transactions.
Aura Gardens and Harmony led the market
Five sales in Aura Gardens and five across Harmony 1 and 2, ten of the month's 17 between them. Both remain the most liquid segments in Tilal Al Ghaf, supported by completed product, family layouts and broad buyer appeal.
Harmony 2's 4BR was Harmony's strongest figure
Two sales averaging AED 9.825M, up 15.93% year-on-year, with one reaching AED 10M. Completed, well-positioned family homes continue to command a clear premium.
Treat the Aura Gardens 3BR average with caution
A single AED 1.395M transaction produces both the 26.41% monthly fall and the 17.84% annual one. The AED 4.14M upper end of the range is the meaningful benchmark and sits within the band the configuration has held all year.
Elan flat year-on-year for a fifth consecutive month
Four transactions split evenly between 3BR and 4BR. Twelve months of level pricing makes Elan the most reliable reference point in the masterplan.
Alaya Gardens delivered the month's standout
A Retreat at AED 17M, reinforcing the appeal of larger, more premium homes below the ultra-prime mansion tier. Both Alaya Gardens tiers sit within a few percent of last year.
The ultra-premium tier stayed quiet
No transfers across Alaya Beach, Elysian Mansion, Serenity Mansion or Lanai Islands. A reflection of access, timing and seller expectation rather than a lack of underlying interest.
For a private view of any of these communities, get in touch.
Source: Dubai Land Department transaction records, May 2026. Figures are presented as market context; small samples and atypical transfers can materially affect averages.
Discuss This Report