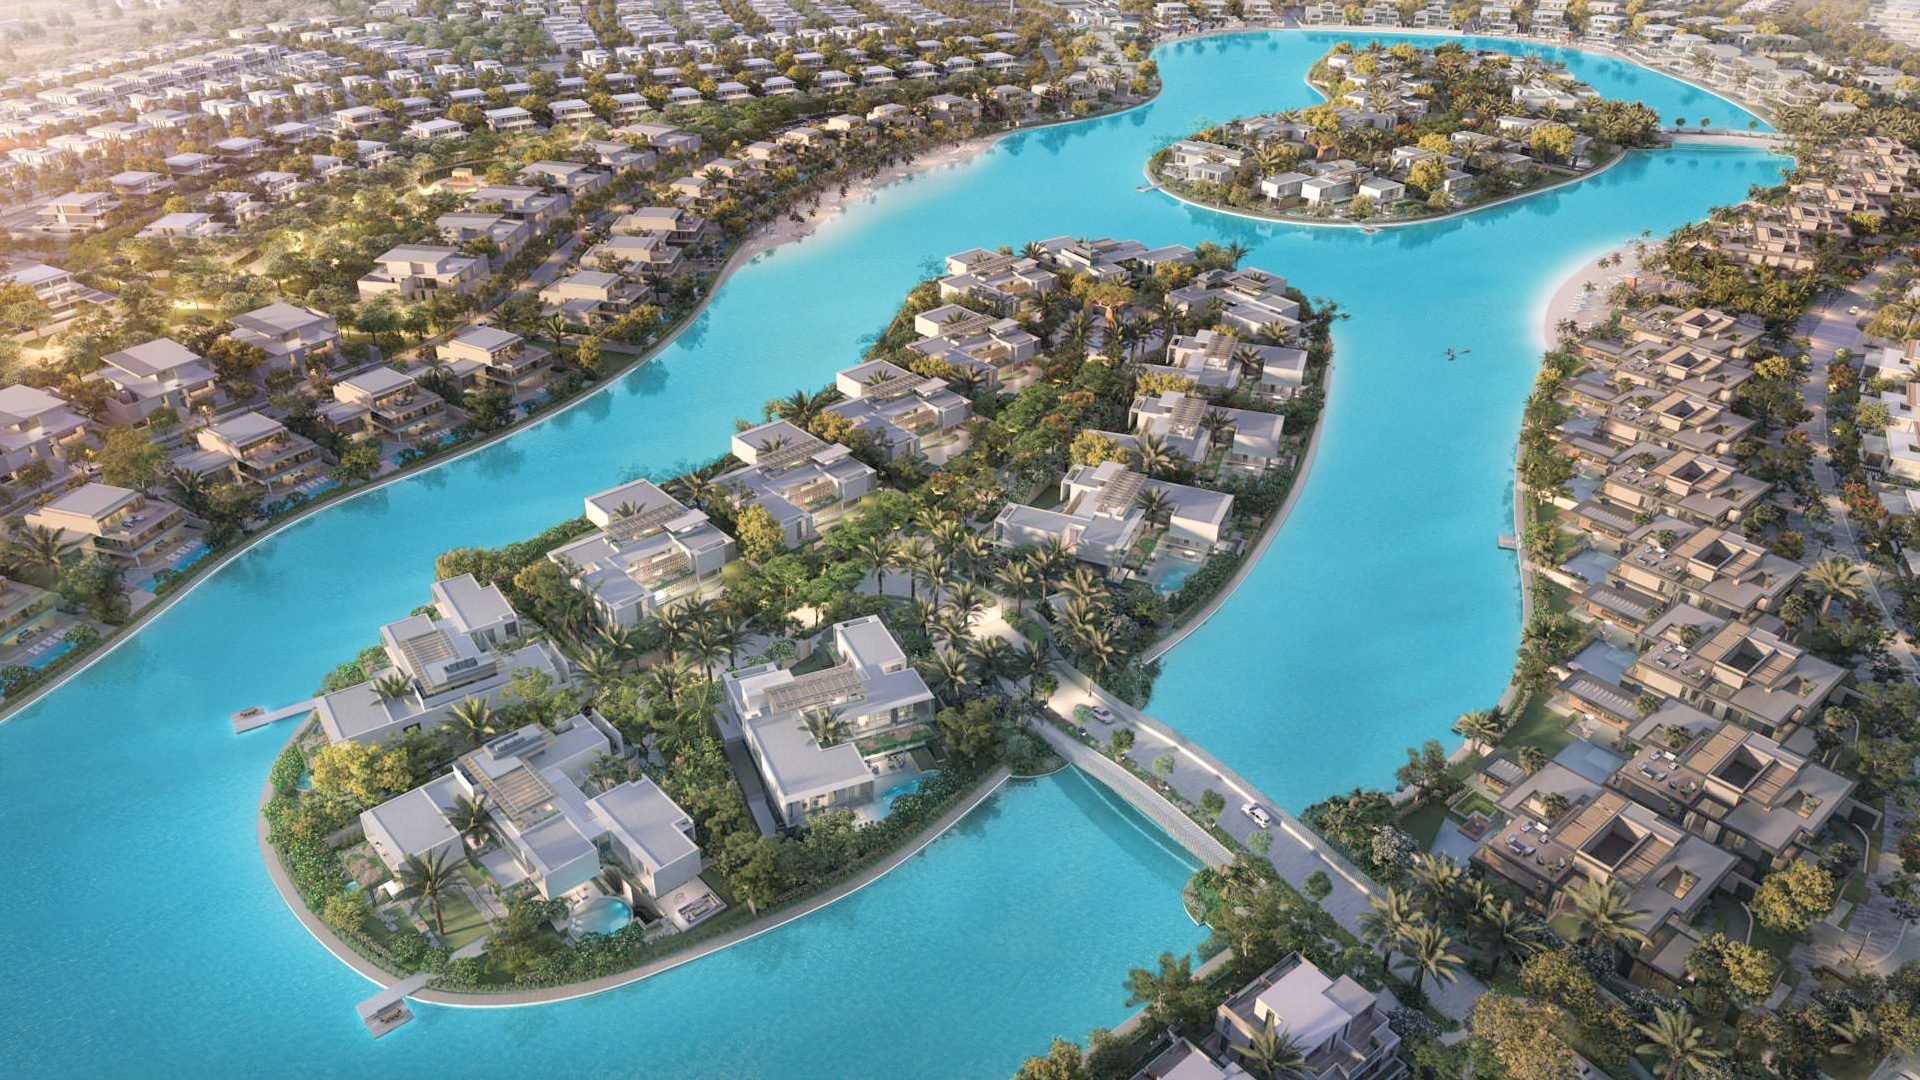
February recorded 36 transactions across Tilal Al Ghaf, up 24% on January and the strongest month of the year so far. Activity was broad and genuinely community-wide rather than concentrated in one pocket, with nine sub-communities transacting. Aura Gardens led on volume with nine sales, followed by Harmony with seven across Phases 2 and 3, and Amara with six. Harmony was the more interesting of the three: buyers moved decisively up the configuration ladder, with 5BR Large, 5BR Signature and 6BR villas all transacting in the same month. Alaya recorded three sales, Alaya Gardens two, and Serenity Mansion added one further mansion print at AED 33.46M. Elysian Mansion recorded no transfers.
Transaction Volume
| Sub-Community | Sales | MoM Change |
|---|---|---|
| Aura Gardens | 9 | +80% |
| Amara | 6 | +200% |
| Elan | 4 | −20% |
| Aura | 4 | +100% |
| Harmony 3 | 4 | +100% |
| Alaya | 3 | −25% |
| Harmony 2 | 3 | No change |
| Alaya Gardens | 2 | −33% |
| Serenity Mansion | 1 | No change |
Elan
Elan recorded four transactions split evenly between 3BR and 4BR, with both configurations flat year-on-year. The modest monthly softening in both tiers is within the normal range for a community of this size and should not be read as a shift. The more telling number is the annual one: Elan pricing has held completely level over twelve months, which is what a mature, fully handed-over cluster looks like once it has found its level. The tight AED 4.45M to AED 4.50M band on the 4BR reinforces that.
Aura & Aura Gardens
Aura Gardens was the most active sub-community in Tilal Al Ghaf with nine sales, transacting across all three of its configurations. The 3BR carried five of those nine. It eased 5.64% on the month but remains 13.53% ahead year-on-year, and the annual figure is the one that matters on a five-sale sample. The 4BR at +15.07% and Twin Villa at +8.77% year-on-year complete a consistent picture across the community. Aura's Twin Villa volume doubled to four sales while the average eased 12.39%. That is a mix effect rather than a repricing: January's average was lifted by a single AED 8.00M sale, and February's wider spread of stock naturally pulled it back. Year-on-year Aura remains 6.39% ahead. The Aura Gardens Twin Villa range of AED 6.40M to AED 6.435M is about as tight as two transactions get, which is a quiet confidence signal.
Harmony
Seven Harmony sales spanning every configuration from 4BR to 6BR, including the first 6BR prints of the year at AED 18.65M and AED 21.00M. This is the most significant thing in the February data. Seven sales across Harmony 2 and Harmony 3, covering every configuration from 4BR through to 6BR in a single month, with the weight of activity in the larger layouts rather than the entry tier. Buyers are moving up the ladder within the community, which is the behaviour you expect once a scheme is genuinely lived in. The Harmony 3 6BR at AED 21M and roughly AED 3,223 per sq ft is the strongest per-foot figure recorded in Harmony this year. The Harmony 2 4BR's 82.18% monthly move is real but needs context: January's Harmony 2 average was pulled down by a single AED 2.00M transaction, so the rebound reflects the return to normal pricing rather than genuine growth of that scale. The 11.52% annual figure is the honest read. With single sales in most tiers, individual monthly moves should be treated as directional. The direction is consistent.
Alaya & Alaya Gardens
Two Alaya Gardens Reserve transfers in a single month is unusual and worth watching. Alaya's three tiers all softened month-on-month, but each remains positive on an annual view, with Reserve up 21.29% and Haven up 6.78%. Monthly softness on single transactions is noise; the annual figures are the signal, and they point the same way they did in January. The two Alaya Gardens Reserve sales are the more interesting development. Reserve is the largest product in that community, and two transfers in one month either reflects stock timing or the beginning of genuine interest in that tier. Early positioning in Reserve is worth tracking closely over the next few months. Alaya is far enough along that buyer interest typically begins to sharpen. I would expect activity to pick up rather than continue easing.
Amara, Serenity Mansion & Elysian Mansion
Six Amara Twin Villa sales in one month, tripling January's volume, with the top of the range reaching AED 10.10M. That is a meaningful demonstration of demand for a community still under construction. The average eased 4.25% on the month, but across a AED 7.70M to AED 10.10M range that reflects the mix of stock absorbed rather than any change in underlying pricing. Year-on-year Amara is 8.35% ahead. This is conviction buying, not opportunistic positioning. Serenity Mansion's Ara+ at AED 33.46M is the community's second mansion print in two months. Still early in construction, but visible pricing at this level sets the tone for what follows. Elysian recorded no transfers in February after January's AED 52M Muse sale. I would attribute that to viewing access rather than pricing: enquiries remain active from buyers who want to see the product before committing.
Notable Sales
Key Takeaways
Volume rose to 36 deals, up 24% on January
The strongest month of the year so far, and broad-based across nine sub-communities. A market transacting with conviction at multiple price points at once, rather than activity concentrated in a single tier.
Harmony transacted at every level from 4BR to 6BR
Including the first 6BR sales of the year at AED 18.65M and AED 21.00M. Buyers are moving up the configuration ladder within the community, which is what happens once a scheme is genuinely lived in.
Aura Gardens was the busiest sub-community
Nine sales across 3BR, 4BR and Twin Villa. All three configurations are positive year-on-year, between +8.77% and +15.07%, which is a more reliable read than any single month.
Amara volume tripled to six sales
Demand emerging organically while the community is still under construction, with the top of the range reaching AED 10.10M. The softer monthly average reflects a wide spread of stock, not a repricing.
Alaya softness is monthly noise, not a trend
All three tiers eased month-on-month but remain positive year-on-year, Reserve by 21.29%. The window where buyer interest typically sharpens is now open.
Two Alaya Gardens Reserve transfers in one month
Unusual for the largest product in that community. Whether this is stock timing or genuine early interest in the tier is worth watching over the coming months.
Elysian quiet after January's AED 52M sale
Access rather than demand. Enquiries remain active from buyers who want to view before committing, and once the community can be freely accessed I expect it to transact quickly.
For a private view of any of these communities, get in touch.
Source: Dubai Land Department transaction records, February 2026. Figures are presented as market context; small samples and atypical transfers can materially affect averages.
Discuss This Report