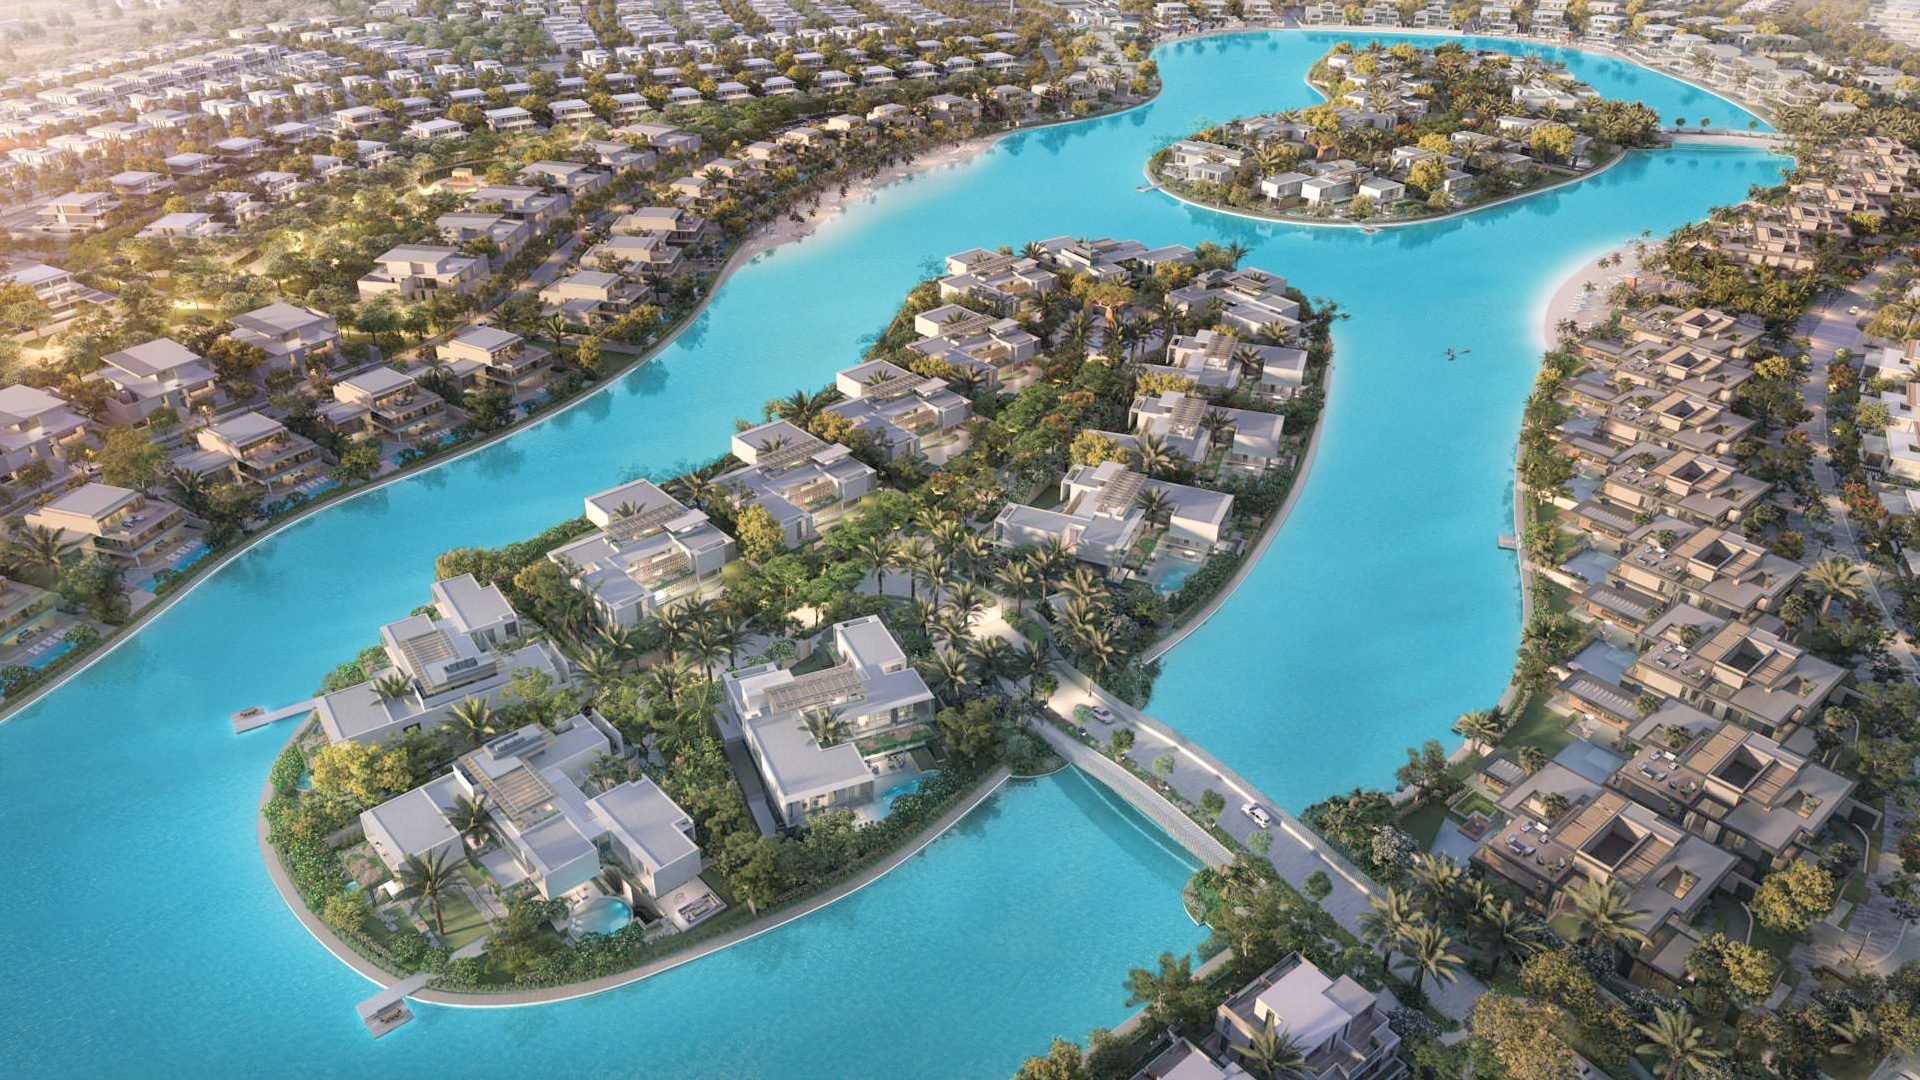
March recorded 26 transactions across Tilal Al Ghaf, down 28% on February's 36. Some of that fall is genuine: a number of transfers registered this month relate to contracts signed in February, and several newly signed agreements have seen delays moving through registration amid the current regional climate. Set against that, pricing was the more instructive part of the month. Elan recorded eight sales, double its February volume, and Aura and Aura Gardens together accounted for a further 12. Every Aura and Aura Gardens configuration moved up, with Aura Twin Villas 12.95% ahead on the month and 19.17% ahead on the year. Amara recorded its highest price of the year. Harmony transacted in its larger configurations. Alaya, Harmony 3 and Serenity Mansion recorded no transfers.
Transaction Volume
| Sub-Community | Sales | MoM Change |
|---|---|---|
| Aura Gardens | 10 | +11% |
| Elan | 8 | +100% |
| Aura | 2 | −50% |
| Harmony 1 | 2 | — |
| Harmony 2 | 1 | −67% |
| Alaya Gardens | 1 | −50% |
| Amara | 1 | −83% |
| Elysian Mansion | 1 | — |
Elan
Elan recorded eight transactions, double its February volume and its strongest month of the first quarter. The 3BR carried five of those eight and rose 6.48% to an AED 4.046M average, its highest level of the year, at roughly AED 1,880 per sq ft. The 4BR added three sales at AED 4.308M, easing 3.72% on the month across a wider AED 3.90M to AED 4.525M spread. Both configurations remain exactly flat year-on-year, as they have in every month of 2026. That is the more useful figure than either monthly move: eight transactions absorbed without any change in annual pricing is a community trading at a settled level rather than finding one. Elan continues to serve the same function it has since completion: the most accessible entry into Tilal Al Ghaf, with enough regular turnover to give buyers a dependable pricing reference.
Aura & Aura Gardens
Aura and Aura Gardens delivered 12 of the month's 26 transactions and every configuration moved up on the month. Aura Gardens transacted ten times across all three of its configurations, its strongest month of the year, with the 4BR up 16.42% and Twin Villas up 10.22% year-on-year. Aura Twin Villas added a further 12.95% on the month to reach an AED 7.15M average, and at 19.17% year-on-year this is now the clearest sustained price trend in the completed segment. The significance of this is worth stating plainly. In a month where overall volume fell substantially, the two most liquid communities in Tilal Al Ghaf both moved up on price. That combination is a demand signal rather than a supply one. Buyers who transacted did so at higher levels, not lower. All four configurations now sit above AED 2,000 per sq ft, which is a threshold Aura Gardens crossed only recently.
Harmony
The Harmony 2 5BR at AED 13.50M was up 36.36% year-on-year and at roughly AED 3,057 per sq ft is the strongest per-foot figure Harmony has recorded outside its 6BR tier. Three sales across Phases 1 and 2, all in the larger configurations. Harmony 1's 5BR Large at AED 16.50M and roughly AED 2,906 per sq ft, and the Harmony 2 5BR at AED 13.50M, both point the same way: the premium end of Harmony is where the pricing strength sits. Volume was lower than February's seven, but February was an unusually broad month, with seven sales spanning every configuration from 4BR to 6BR. Three sales concentrated in larger homes is a normal distribution for a community this size, and with single sales in each tier the annual figures carry more weight than the monthly ones.
Alaya & Alaya Gardens
A quieter month for Alaya, with a single Alaya Gardens Retreat at AED 18.00M providing the tier's data point. Alaya recorded no transfers after three in February. Owners in this community have largely completed their payment schedules and can comfortably hold rather than transact now, particularly while the current climate keeps some buyers on the sidelines. The Alaya Gardens Retreat at AED 18.00M and roughly AED 2,197 per sq ft holds close to the level established in January. The Retreat continues to occupy a clear position in the market: larger than completed Harmony stock, without stepping into the mansion bracket.
Amara, Elysian Mansion & Serenity Mansion
Amara's single Twin Villa at AED 10.50M is the highest price recorded in that sub-community so far this year. It arrived on lower volume, which is the shape of conviction buying: fewer buyers, but the ones transacting are paying up. Construction progress is now clearly visible on entering the community, and that visibility is doing real work on pricing. The Elysian Maia at AED 21.50M is the community's second transfer of the year, following January's AED 52M Muse. The two are not comparable products, and the gap between them illustrates how wide the Elysian range is across its layouts. At roughly AED 2,015 per sq ft the Maia reflects current viewing constraints more than the scheme's trajectory. Once full access for viewings becomes possible, I expect both transaction volume and pricing to move.
Notable Sales
Key Takeaways
Volume fell to 26 deals, down 28% on February
Read this in context. February was the strongest month of the year at 36 transactions, and a portion of March's transfers relate to contracts signed before the escalation of regional tensions, while some recently signed deals have faced registration delays. Elan alone doubled its volume to eight. The count reflects the climate more than the level of demand.
Pricing rose while volume fell
This is the month's most important feature. Every Aura and Aura Gardens configuration moved up, Amara set a new high, and Harmony's premium tiers held. A market softening on demand does not behave this way.
Aura and Aura Gardens delivered 12 of 26 sales
Aura Twin Villas up 12.95% on the month and 19.17% on the year, Aura Gardens 4BR up 16.42% year-on-year. All four configurations now trade above AED 2,000 per sq ft.
Amara reached a new high at AED 10.50M
Up 24.26% on the month on a single transaction. Visible construction progress is supporting pricing, with buyers paying up rather than waiting.
Harmony's strength sits in the larger configurations
All three sales were 4BR and above. The Harmony 2 5BR at AED 13.50M was up 36.36% year-on-year, at roughly AED 3,057 per sq ft.
Elysian recorded its second transfer of the year
A Maia at AED 21.50M, following January's AED 52M Muse. The spread between the two reflects the range of layouts rather than any movement in the scheme. Improved viewing access is the constraint to watch.
Alaya quiet after a strong start to the year
No transfers after three in February. Many owners here have completed their payment schedules and can hold rather than sell into the current climate.
For a private view of any of these communities, get in touch.
Source: Dubai Land Department transaction records, March 2026. Figures are presented as market context; small samples and atypical transfers can materially affect averages.
Discuss This Report